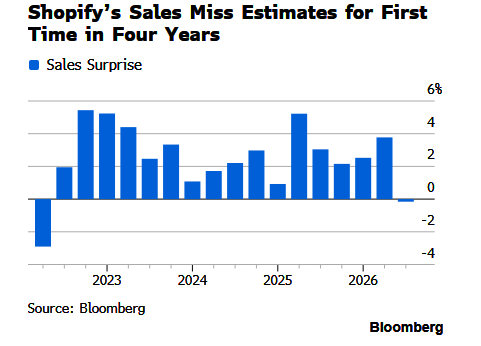
Shopify shares crashed in premarket trading in New York after the first sales miss since 2022. Investors focused on subscription revenue that fell short of the Bloomberg Consensus estimate, and Wells Fargo analysts pointed to gross
margin headwinds due to AI.
Third quarter revenue rose 32% to $3.74 billion, falling just short of the consensus estimate of $3.75 billion. Subscription Solutions revenue missed, while Merchant Solutions, its largest business, was roughly in line. Gross merchandise volume also missed estimates.
Here's a snapshot of 3Q earnings:
- Revenue $3.74 billion, estimate $3.75 billion (Bloomberg Consensus)
- Monthly recurring revenue $230 million, estimate $229.9 million
- Merchant Solutions revenue $2.91 billion, estimate $2.9 billion
- Subscription revenue $836 million, estimate $850.2 million
- Adjusted EPS 49c, estimate 48c
- Operating income $568 million, estimate $523.9 million
- Total operating expenses $1.21 billion, estimate $1.26 billion
- Gross merchandise volume $119.15 billion, estimate $120.08 billion
The subscription revenue miss raises questions about Shopify's ability to generate additional revenue from merchants.

Shopify expects fourth-quarter revenue to grow at a low-30s percentage rate from one year ago, with gross profit dollars rising at a high-20s pace. Operating expenses are projected at 29% to 30% of revenue, while the free cash flow margin is expected to remain consistent with 4Q25.
Wells Fargo analyst Ken Gawrelski: "Gross margin headwinds worsening; see Sidekick/AI inference as likely cause."

Gawrelski highlights year-over-year changes in revenue from Subscription Solutions and Merchant Solutions units.

Shopify shares fell as much as 20% in New York premarket trading as investors hoped for stronger earnings results.
Around 8:30 a.m. EST, shares were down 15%.

"We believe the ~15% premarket selloff largely reflects heightened investor expectations heading into the quarter," Truist analyst Terry Tillman wrote in a note.
Source link