Our "Great Rare Earth Disconnect" note earlier this week highlighted the widening gap between elevated rare earth prices and tumbling junior miners and producers. William Blair rare-earths analyst Neal Dingmann has also weighed in on the forces driving the selloff.
"Revived rate-hike fears, hot CPI, and other macro concerns along with rare earth headline and company-specific concerns have notably hurt the largely high-beta rare earth group in recent weeks," Dingmann wrote.
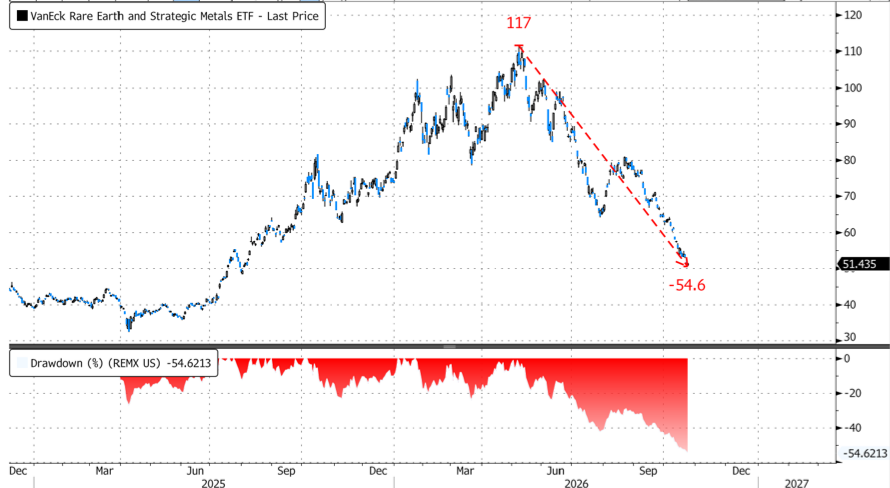
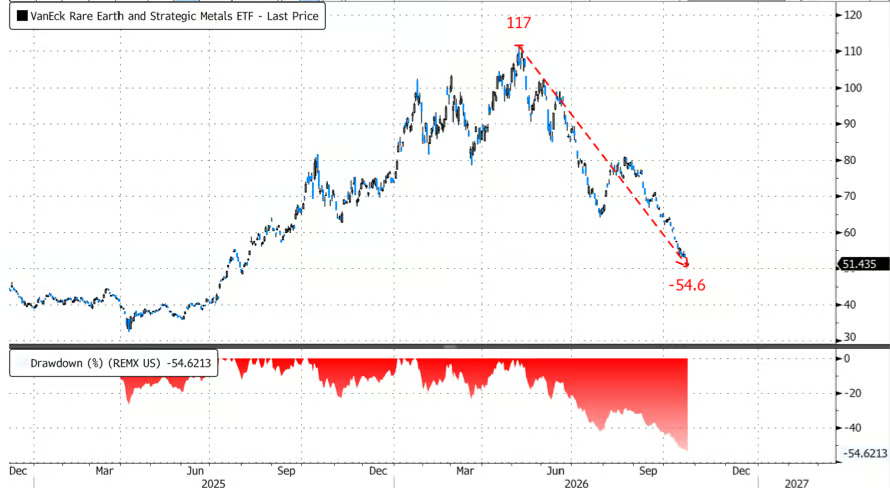
The VanEck Rare Earth and Strategic Metals ETF (REMX) has lost more than half its value since peaking in May, even as commodity prices remain strong and demand for conflict-free Chinese supplies continues. That divergence raises one key question: how much of the selloff reflects deteriorating fundamentals, and how much reflects misplaced expectations of easing supply constraints?
Dingmann wrote that investors may be overestimating the relief a thaw in US-China relations would bring.
"Specifically, many investors anticipate (incorrectly, in our opinion) cooling rare earth supply-scarcity with improved U.S./China relations ahead of the next Trump/Xi meetings in November (in China) and December (G20 in Florida)," he said.
He continued:
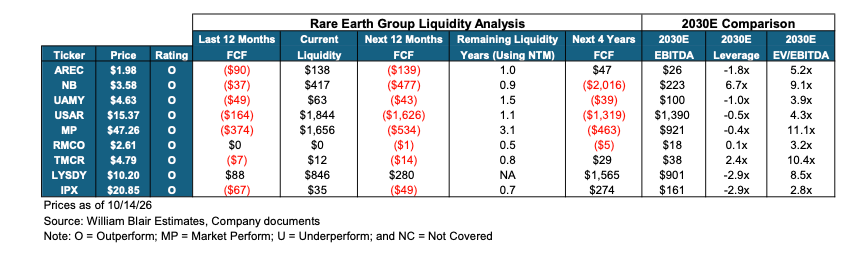
Further, investors appear to have increased liquidity concerns given heavy spending requirements against minimal near-term revenue and milestone-based government funding that for many companies has yet to be collected.
While we continue to point to strong REE prices and potential long-term volumes, many companies are not yet benefiting from the high levels given limited current output at the mine or processing, alloy, and magnet facilities.
While we continue to believe the insatiable demand for REE provides a strong long-term backdrop for much of the group, driving many of our Outperform ratings, we remain cautious in the near term over much of the group given the large stock price declines in many REE companies, as it adds to near-term liquidity concerns.
We continue to favor MP Materials and Lynas Rare Earths most in the near term given the former's attractive offtake agreements and price floors along with the latter's limited funding needs and long-term track record.
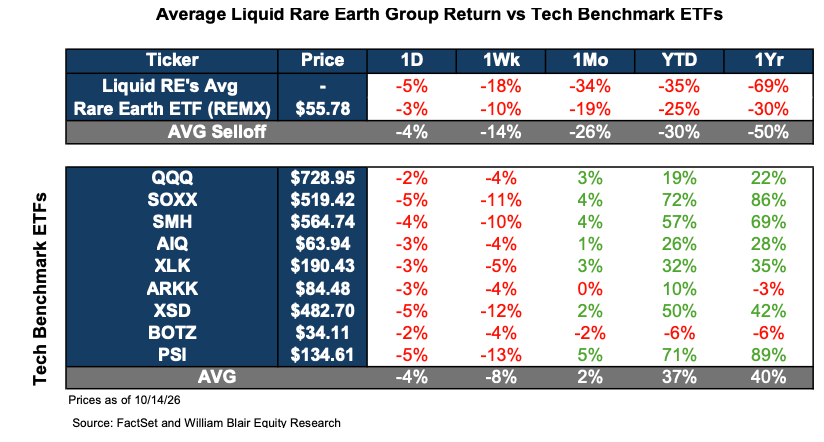
The firm's basket of seven miner stocks (MP, LYSDY, AREC, IPX, NB, UAMY, and TMCR) has tumbled about 30% on average over the previous month at the time of the report. He said interest rate concerns, inflation pressures and expectations of improving US-China relations have compounded worries about spending requirements and delayed government funding.
Lower share prices are fueling another major concern for these miners: equity financing is more costly for companies building capital-intensive mines, processing plants and magnet facilities. He warned that some of these miners could hit a "debt wall," substantial shareholder dilution or material project delays.
What changed with investors?
Investors appear to continue to shift their focus from upside driven by government support and strategic value toward actual production and cash flow, causing growing concerns about how capital-intensive projects will be funded at lower equity values.
With equity prices significantly lower, raising the capital needed to fund these projects becomes increasingly dilutive, leaving companies that still require significant external funding with fewer options.
From here, we could see a rebound if Chinese restrictions are renewed, government funding, or company-specific production milestones restore urgency to the ex-China buildout. On the flip side, another trade extension, company project delays, or funding delays could keep valuations under pressure and further increase funding risk, dilution risk, and overall company finance risk
Canaccord's critical minerals team, led by Reg Spencer, also questioned the scale of the selloff, highlighting the disconnect between elevated rare earth prices and sharp declines across junior miner and established producer stocks.
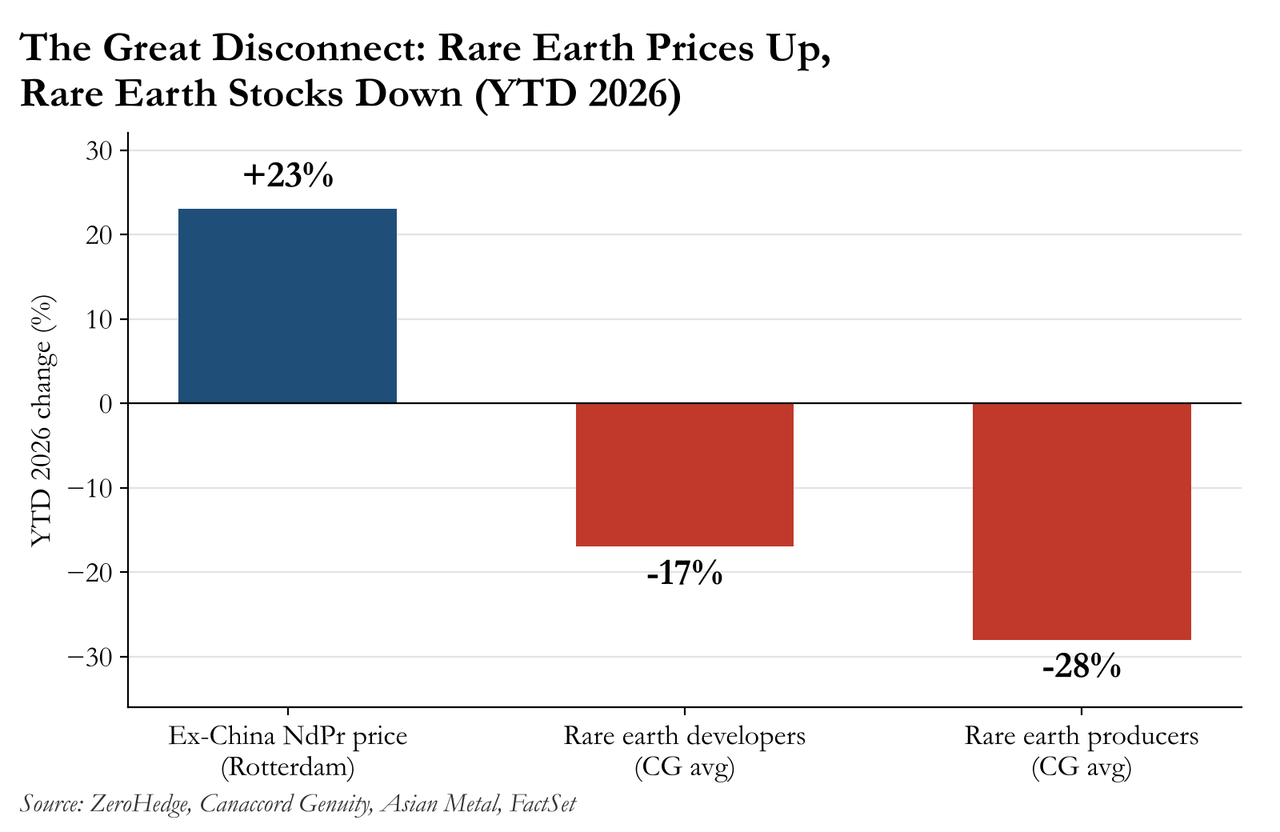
Potential catalysts for renewed investor interest across the space include tighter Chinese export restrictions, government funding commitments and production milestones that demonstrate commercial progress. Until then, balance-sheet strength and execution remain key differentiators. Producers with operating assets and robust liquidity to fund their growth plans appear better positioned to weather the shakeout and participate in a recovery once bears are down and dragging the space down.
Source link